


Procurement Fraud: Types, Warning Signs, and How to Prevent It
Mekari Insight
- Procurement fraud can occur at different stages of the purchasing process, from supplier selection and bidding to contracting, invoicing, and payment.
- Common schemes include bid rigging, conflicts of interest, fake vendors, false invoices, duplicate billing, and contract manipulation.
- Finance and procurement teams can detect warning signs by reviewing supplier information, bidding patterns, contract changes, supporting documents, and payment activity.
- Mekari Expense helps procurement and finance teams manage these risks through vendor controls, approval workflows, audit trails, and centralized procurement records.
Procurement fraud can happen when someone manipulates a purchasing process to gain an improper financial benefit. The risk can involve employees, suppliers, contractors, or collusion between parties, and it can appear during vendor selection, bidding, contracting, invoicing, or payment.
A procurement process can look routine while still containing gaps that allow fraud to go unnoticed. A supplier may submit inflated pricing, competing bidders may coordinate their bids, or an employee may approve a vendor with a personal connection.
This guide explains the common types of procurement fraud, the warning signs finance and procurement teams should watch for, and the controls companies can use to detect and prevent it.
What Is Procurement Fraud?
Procurement fraud is dishonest or improper conduct involving the purchase of goods or services. It can occur across the procurement cycle, including sourcing, tendering, vendor selection, contracting, invoicing, and payment.
The people involved can be internal employees, external suppliers, or multiple parties working together. The objective may be to secure a contract unfairly, inflate costs, divert funds, or receive an unauthorized benefit.
Common examples include bid rigging, bribery and kickbacks, conflicts of interest, fake vendors, false invoices, duplicate billing, and product substitution.
How Can You Detect Procurement Fraud?
Detecting procurement fraud requires looking across the purchasing process rather than reviewing a single transaction in isolation. Finance and procurement teams can compare supplier information, bidding activity, contract terms, documents, and payment patterns to identify inconsistencies.
1. Review Supplier Information
Check the supplier’s legal identity, ownership, registration details, previous performance, and relationship with the company. Repeated awards, unusual supplier relationships, or incomplete documentation may require further review.
2. Review Bidding Patterns
Compare bids for unusual similarities in pricing, formatting, timing, or submission patterns. Limited competition, repeated winners, or losing bidders later receiving subcontracting work can also warrant investigation.
3. Compare Prices and Contract Terms
Check whether quoted prices, quantities, and contract terms are consistent with approved budgets, previous purchases, market information, or the agreed scope. Large unexplained differences should be reviewed before approval.
4. Match Orders, Deliveries, and Invoices
Compare purchase orders, delivery or receipt records, and invoices before payment. This can help identify duplicate billing, unsupported charges, incorrect quantities, or goods and services that were not received.
5. Monitor Changes After Contract Award
Review changes to pricing, scope, quantities, timelines, and payment instructions after a contract has been awarded. Frequent or poorly justified changes can indicate attempts to alter the commercial terms after the original decision.
6. Review Payment and Transaction Patterns
Look for duplicate payments, repeated transactions with similar amounts, unusual payment timing, or changes to supplier bank details that have not gone through the normal verification process.
Baca Juga: Procurement Compliance & Governance Framework Guide
What Are the Warning Signs of Procurement Fraud?
A single irregularity does not necessarily mean fraud. The stronger signal is a recurring pattern across suppliers, bids, contracts, approvals, or payments.
| Red flag | What to review |
|---|---|
| Repeated awards to one supplier | Check whether the supplier consistently wins without a clear competitive advantage. |
| Limited or unusual competition | Review whether bids appear coordinated or whether specifications restrict competition without clear justification. |
| Similar bid patterns | Compare pricing, formatting, submission timing, and other similarities between competing bids. |
| Frequent contract changes | Review repeated price, scope, quantity, or timeline changes after award. |
| Contract splitting | Check whether purchases are divided into smaller transactions without a clear business reason. |
| Missing or incomplete documents | Review purchases that lack required invoices, contracts, approvals, or delivery records. |
| Unusual supplier relationships | Check for undisclosed personal, financial, or business connections between employees and suppliers. |
| Duplicate or inflated invoices | Compare invoice numbers, amounts, quantities, and supporting documents. |
| Unexpected payment changes | Independently verify new bank details or changes to payment instructions. |
| Poor-quality or substituted goods | Compare delivered goods or services with the agreed specifications and contract terms. |
| Rushed approvals | Review urgent requests that bypass normal procurement or approval procedures. |
Read more: 7 Vendor Fraud Schemes: How to Identify and Prevent It
What Are the Most Common Types of Procurement Fraud?
Procurement fraud can take different forms depending on where the manipulation happens. Some schemes affect supplier selection, while others appear after a contract has already been awarded.
| Type of procurement fraud | How it happens |
|---|---|
| Bid rigging | Suppliers coordinate bids or manipulate the tender process to influence the winner or price. |
| Conflict of interest | An employee has an undisclosed personal or financial relationship with a supplier involved in the procurement decision. |
| Bribery and kickbacks | A supplier provides money, gifts, services, or other benefits in exchange for favorable treatment. |
| Phantom vendors | A fictitious or unauthorized supplier is created so fraudulent purchases or invoices can be processed. |
| Invoice fraud | A supplier submits false, inflated, or unsupported invoices for goods or services. |
| Duplicate billing | The same goods, services, or invoice are billed more than once. |
| Product substitution | A supplier delivers goods or materials that differ from the agreed specifications or quality. |
| Contract manipulation | Contract terms, prices, scope, or quantities are changed without proper justification or approval. |
Prevention starts with controls that make it harder to bypass procurement procedures and easier to review unusual activity. The controls should cover supplier onboarding, purchasing, approval, payment, and ongoing monitoring.
1. Separate Procurement Responsibilities
Assign different responsibilities for supplier onboarding, purchasing, invoice approval, and payment where practical. Separating these duties reduces the chance that one person can create, approve, and pay for a fraudulent transaction.
2. Perform Supplier Due Diligence
Verify supplier identity, business registration, ownership information, relevant credentials, and previous performance before onboarding. Repeat the review when supplier risk or business circumstances change.
3. Standardize Procurement and Approval Workflows
Require purchases to follow defined procurement procedures and approval thresholds. This creates a consistent record of who requested, reviewed, and approved each transaction.
4. Match Procurement Documents
Where applicable, compare purchase orders, goods received records, and invoices before payment. Investigate differences in price, quantity, or delivery rather than approving exceptions automatically.
5. Monitor Suppliers and Transactions
Review supplier activity, payment patterns, duplicate transactions, and unusual pricing. Analytics can help finance and procurement teams identify transactions that need a closer look.
6. Maintain an Audit Trail
Keep procurement requests, approvals, supplier records, contract changes, invoices, and payment information in a traceable record. A complete history makes unusual transactions easier to investigate.
7. Train Employees and Provide Reporting Channels
Train employees to recognize conflicts of interest, suspicious supplier behavior, unusual bidding patterns, and other warning signs. Employees should also have a clear and safe way to report concerns. CIPS specifically recommends fraud checks within supplier evaluation, employee training, formal policies, and regular review of procurement processes.
Read more: Procurement Maturity Model: 4 Stages to Procurement Excellence
What Should You Do If You Suspect Procurement Fraud?
When a transaction appears suspicious, the priority is to prevent further financial exposure while preserving the information needed to investigate.
1. Pause the Transaction
Where appropriate, place the payment, purchase, or contract change on hold until the issue has been reviewed.
2. Preserve Relevant Records
Keep the invoices, purchase orders, bids, contracts, approvals, emails, messages, and transaction records related to the case.
3. Verify the Facts Independently
Confirm the supplier, transaction details, delivery records, payment instructions, and approval history through independent sources rather than relying only on the information provided in the original request.
4. Escalate Through the Appropriate Process
Refer the issue to the responsible finance, procurement, compliance, internal audit, or legal team based on the company’s procedures.
5. Review the Control Gap
After the issue has been assessed, identify which control failed or was bypassed and determine whether similar transactions require review.
How Does Mekari Expense Help Prevent Procurement Fraud?
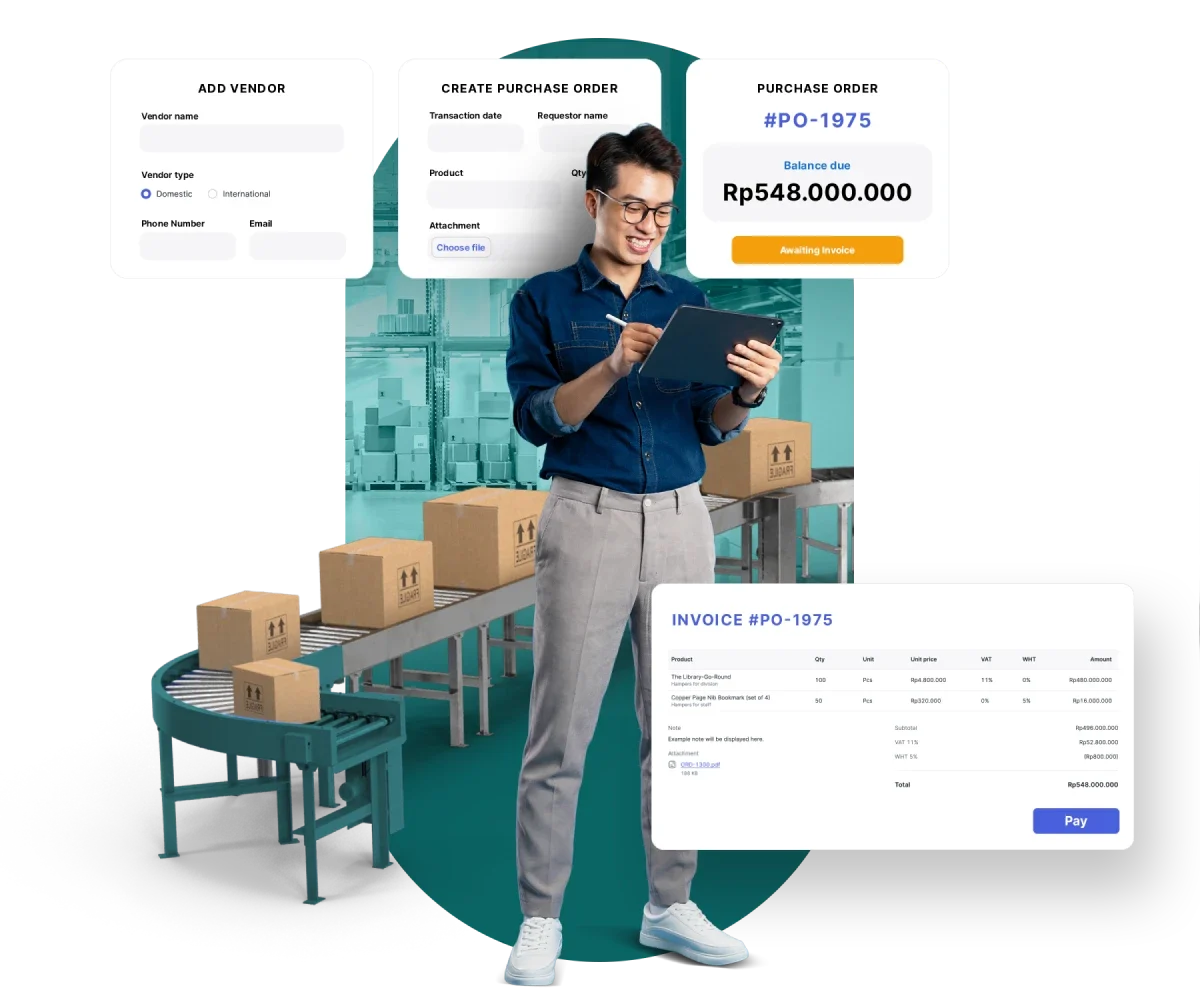
Procurement controls depend on consistent supplier records, defined approval processes, and visibility across purchasing activity. Mekari Expense supports these controls through a centralized procurement workflow.
Its procurement features help teams manage:
- Verified vendor records to keep supplier information within a controlled database
- Standardized product catalogs and pricing information
- Multi-level approval workflows for purchase requests and purchase orders
- Audit trails for procurement activity and approvals
- Payment and deposit tracking
- Centralized monitoring across branches and locations
For businesses reviewing procurement risks across supplier selection, purchasing, and payment, these controls provide a clearer record of how each transaction moves through the procurement process.
References
Linkurious. ‘’Procurement fraud: How to spot common schemes’’